

This article is free to read. For more of our work on European technology and venture capital, consider becoming a premium subscriber for €9.99 a month or €89.99 a year.
Interested in group subscriptions? Contact us.
It is with great excitement that we bring you The Venturist’s Robotics 65: our selection of European robotics companies we believe will alter the future. We expect robotics to have a profound effect on our economies and surroundings in the coming years. Studying these companies have made the future feel rather less distant.
The selection is the product of weeks of research and recommendations from investors.
Robotics, everywhere
Robotics has been around long enough to loom in the back of our minds, yet the sentiment is that only now we’re approaching the true inflection point. The causes of this are multifold:
Major advances in computer vision and Vision-Language-Action (VLA) models, helping robots interpret their surroundings and act on instructions.
Falling component costs, making hardware development more affordable.
Pressure to re-industrialise, alongside ageing workforces and labour shortages.
Robotics are still blue-ocean.
Specialised applications remain relatively uncrowded, where the difficulty of building hardware still discourages many founders from throwing their hat in the ring.
Newfound suppliers’ willingness to support smaller, iterative batch productions
50–70% of the cost of a robot application can come from programming and integration. AI’s expected to halve those costs.
The growing interest has been accompanied by a surge in venture investment. Whether investors followed that enthusiasm or caused it is harder to say. Over the five years shown below, quarterly deal counts roughly doubled, while investment deal value climbed sharply.
Our selection
We started with a handful of eligibility rules to narrow the pool, then turned to recommendations, further research and our own preferences to choose our favourites.
Our criteria were:
A minimum financial threshold. We considered companies with either a valuation of at least €10 million or annual revenue of at least €1 million. This meant leaving out some wonderfully ambitious younger teams, but ensured that every company had reached a minimum measurable threshold.
Private, unlisted and not acquired. We focused on independent private startups, where the most audacious ideas are being pursued. This naturally excluded the old guard, such as ABB and KUKA. Some companies on our list are approaching maturity, but all remain unlisted and have not been acquired.
A strong European foothold. We wanted this selection to show what Europeans are building and help us imagine how Europe might look and function in the future. Companies therefore needed either a legal headquarters in Europe or deeply symbiotic European presence and roots.
This involved some judgment. We excluded 1X Technologies, whose centre of gravity has shifted towards the US, while keeping companies such as Brightpick and Medical Microinstruments, which retain substantial European operations despite having US headquarters.
No defence-only companies. We considered defence companies only where their technology also has civilian applications. Defence is booming and deserves its own selection. Including it in full would have squeezed out companies whose work could have a greater bearing on Europe’s civilian economy and infrastructure. This excluded Helsing and STARK, among others.
We also considered recent funding rounds, momentum, commercial traction and investor quality. Beyond the eligibility rules, the final selection reflects our own judgment.
What you get in the database
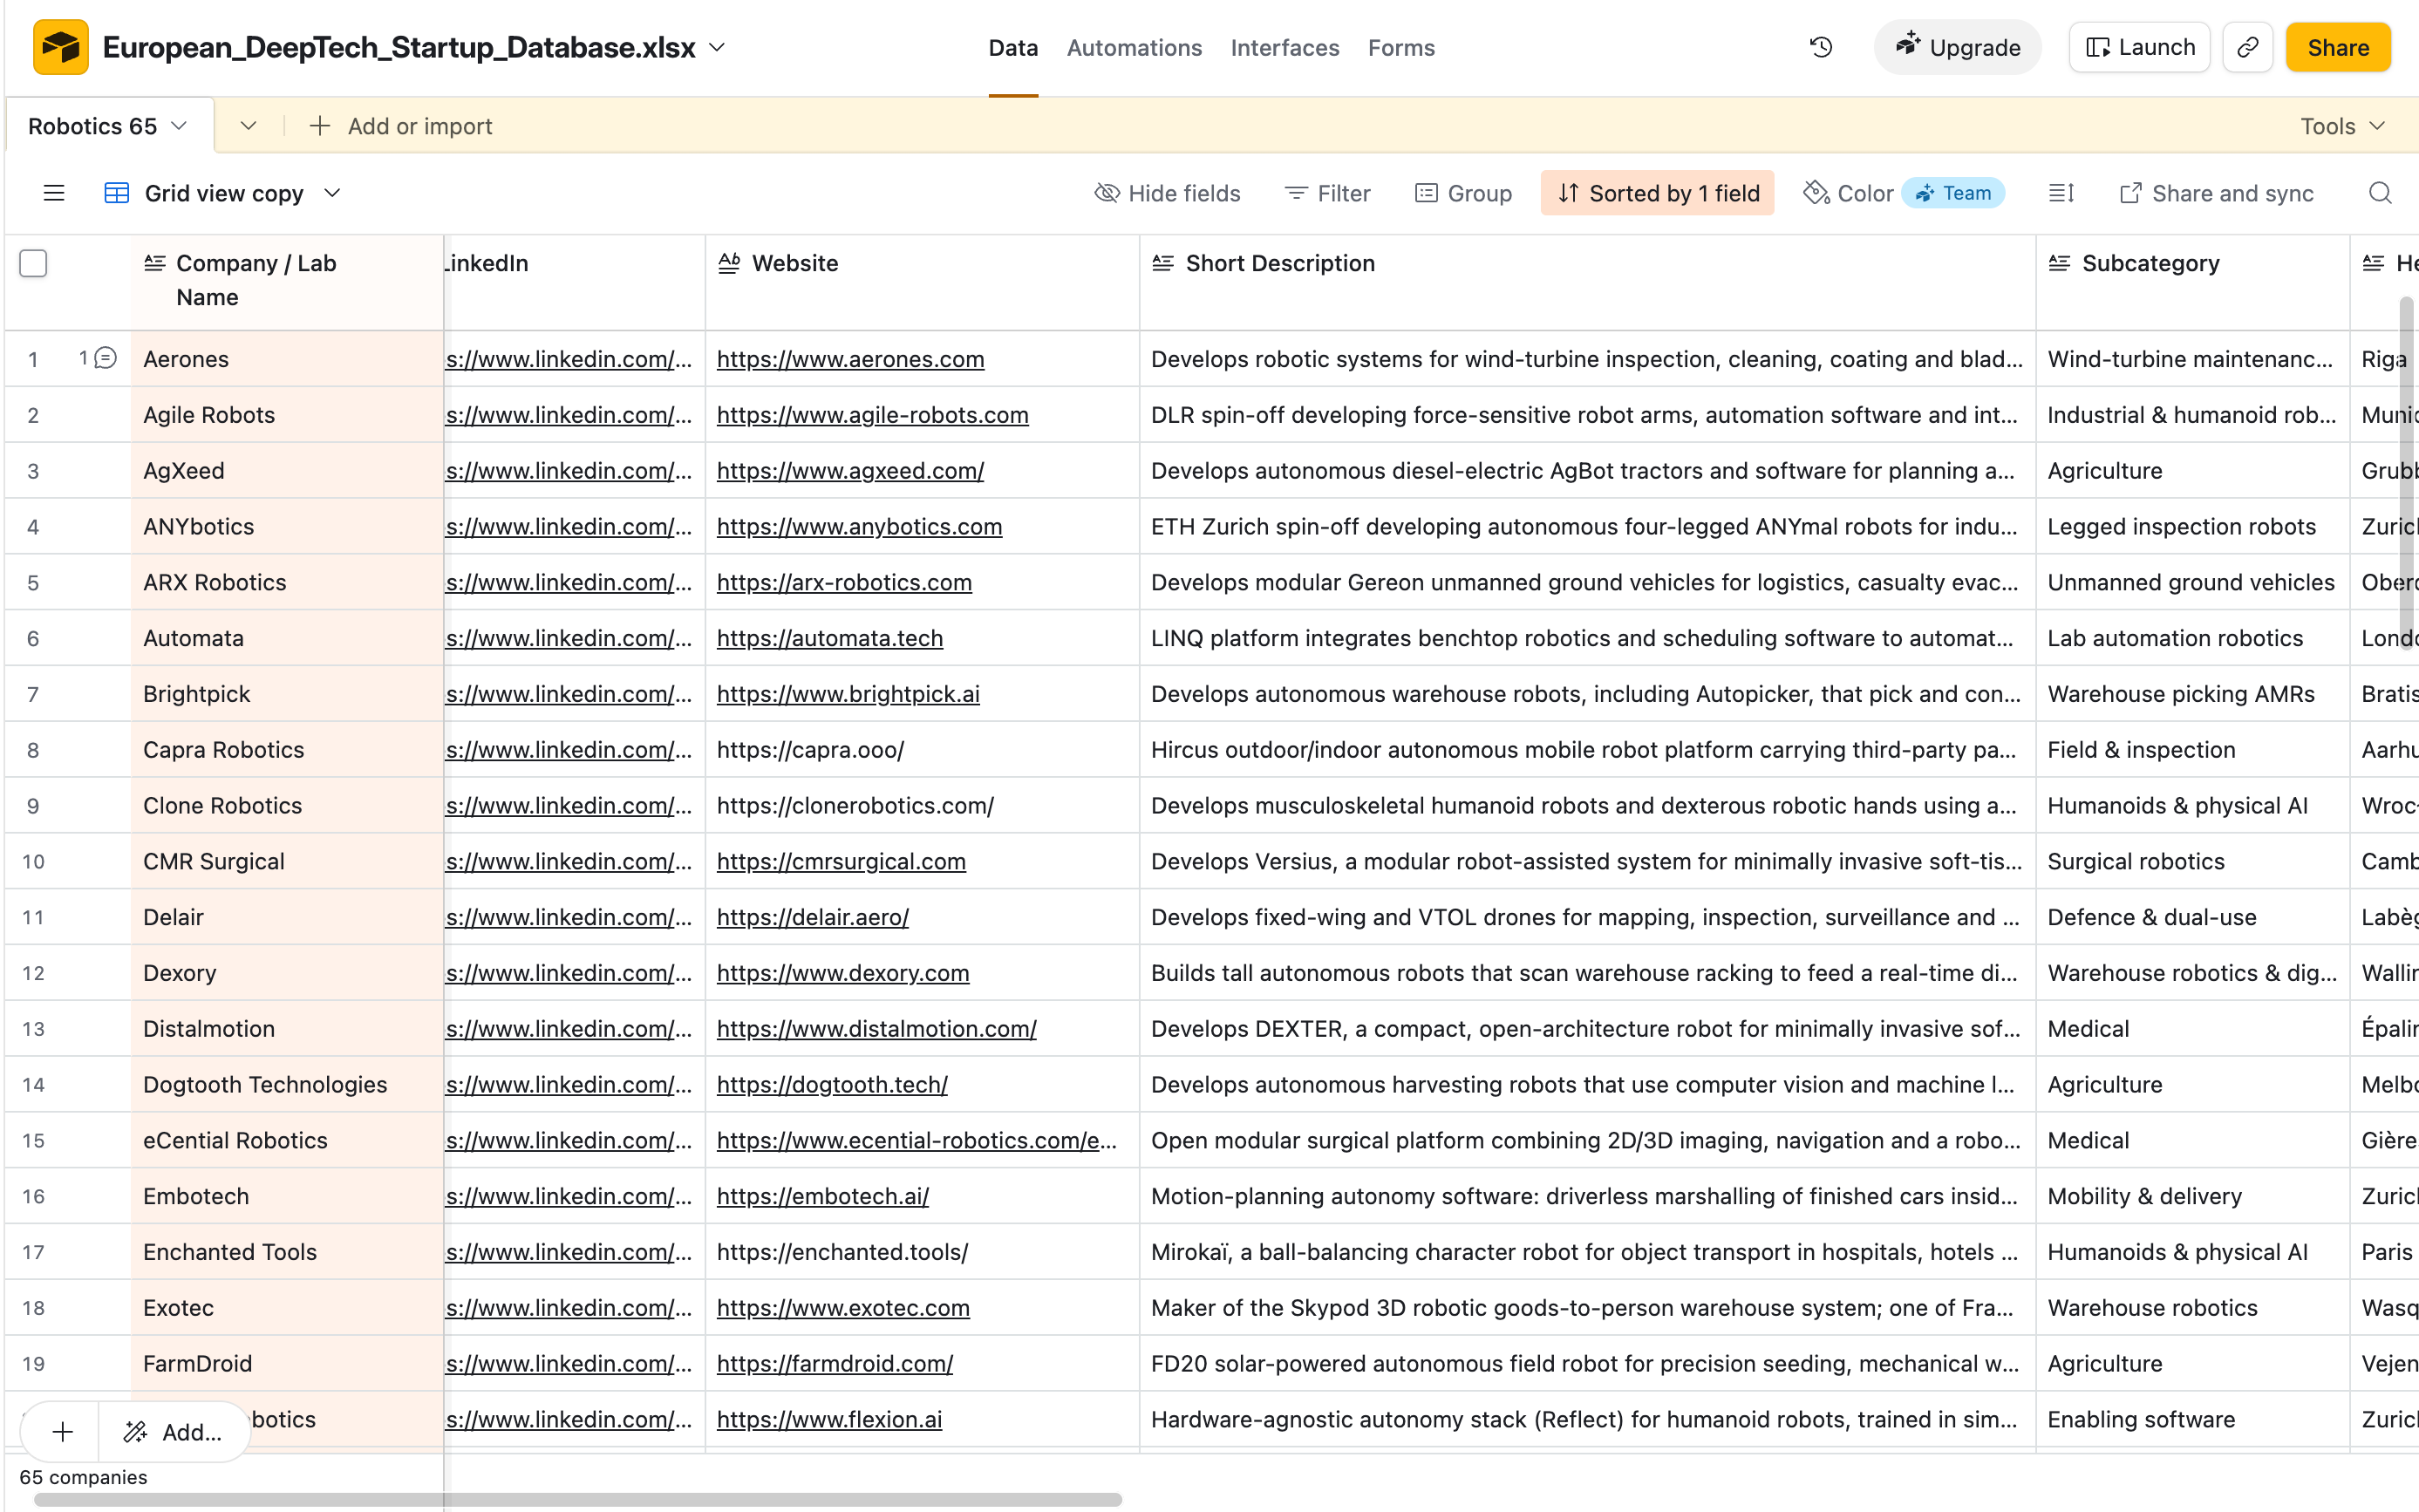
Click the button below for an abundance of robotics, complete with the following particulars:
Company names: our selection of Europe’s most important and promising robotics companies.
Websites and LinkedIn pages.
Short descriptions: what each company does, with the context needed to understand it.
Subcategory.
Headquarters city and country.
Founding year.
Founding team.
Total funding to date.
Latest funding round.
Key investors.
Europe’s Robotics 65 & Key Trends
Studying Europe’s robotics gems, we’ve noticed a few trends:
Industry and logistics are still the main market. Roughly one in five companies focuses primarily on factory or warehouse automation. This was to be expected, as these environments involve highly repetitive work and are therefore well suited to automation.
Much of the opportunity is in brownfield robotics. Multiple startups retrofit existing equipment with their technology rather than wait for customers to replace their physical capital. This can drastically speed up adoption.
Investors’ appetite to go all-in has increased. Our database records multiple nine-digit funding rounds for startups founded as recently as 2024, and eight-digit rounds for companies still establishing commercial traction.
Startups are increasingly selling outcomes. Rather than have customers buy the hardware and take responsibility for operating it, vendors run the robots themselves and bill monthly, per hour or per project. Some do this through a RaaS model. This brings robotics companies into direct competition with incumbent service providers, not only other robotics companies.
AI attacks what used to be robotics’ greatest weakness: flexibility. Historically, robots worked best in highly controlled environments because they struggled when the goalposts move, which is why industrial robotics concentrated in sectors like automotive manufacturing.
Multiple companies in our selection approach the issue from intelligence layer, making robotics more adaptable and cheaper to deploy. We expect this to open a vast long industrial tail of application (think SMEs and factories with less repetitive work), as well as more of the consumer market.1General-purpose robots are a huge new trend. Among the 46 companies founded before 2021, only two (4%) fall into our humanoid or general-purpose category. Among the 19 founded in 2021 or later, eight (42%) do, six of them founded in epochal 2024–25.
Robotics will aid humans in most categories, not replace them. Healthcare and inspection together account for nearly a third of our selection. Many of these companies amplify human efficacy rather than replace it, allowing more precise work or keeping people out of hazardous environments. They vastly de-risk human jobs.
Big hubs cluster close to universities. Zurich counts eight companies in our selection, all with direct ETH lineage, usually through spin-offs. Other companies have roots in TU München, EPFL, Oxford, TU Eindhoven, TU Dresden and Stuttgart. 2
Consumer market is absent. For now! Vast majority of our database companies sell to businesses, government, labs, hospitals, etc. Their focus is high-value B2B tasks with clear ROI, rather than discretionary consumer ownership. Some general-purpose companies might be implicitly betting that this changes eventually.
General-purpose robots are being aimed at very specific customers. Most humanoid and general-purpose companies in our selection actually aim at specific customers, for example logistics and manufacturing. The robotics industry may be moving towards general-purpose machines, but commercialisation remains highly vertical.3
On Europe, the US and China
Although industrial robotics is already a relatively mature category, its growth is not yet exhausted. More than five million industrial robots were operating worldwide at the end of 2025. To put that in perspective, there were 454,000 in 1990 and 1.06 million in 2010. China was the absolute hegemon of new installations in 2025, with 59% of the roughly 603,000 installed worldwide.
A few details caught our attention:
Europe’s installed fleet is roughly twice the size of America’s, but new European installations fell in 2025 while American installations grew.
The EU-27 has a higher robot density per manufacturing worker than China, with Germany almost 3x-ing the Chinese figure.
Europe accounted for 12% of new installations in 2025, including 10% in the EU-27, compared with China’s 59% and the US’s roughly 6%.
Europe holds 17% of total installations, compared with Chinese 40%, and US’s 8%
Chinese 2025 installations almost match US’s entire robotics base
More on Robotics 65
We ran a series of analyses on our database with the purpose of understanding this field even better. We created an overview of what we’ve found studying these avant-garde, anomalous companies.
Results are laid out below.
Company headcounts and valuations
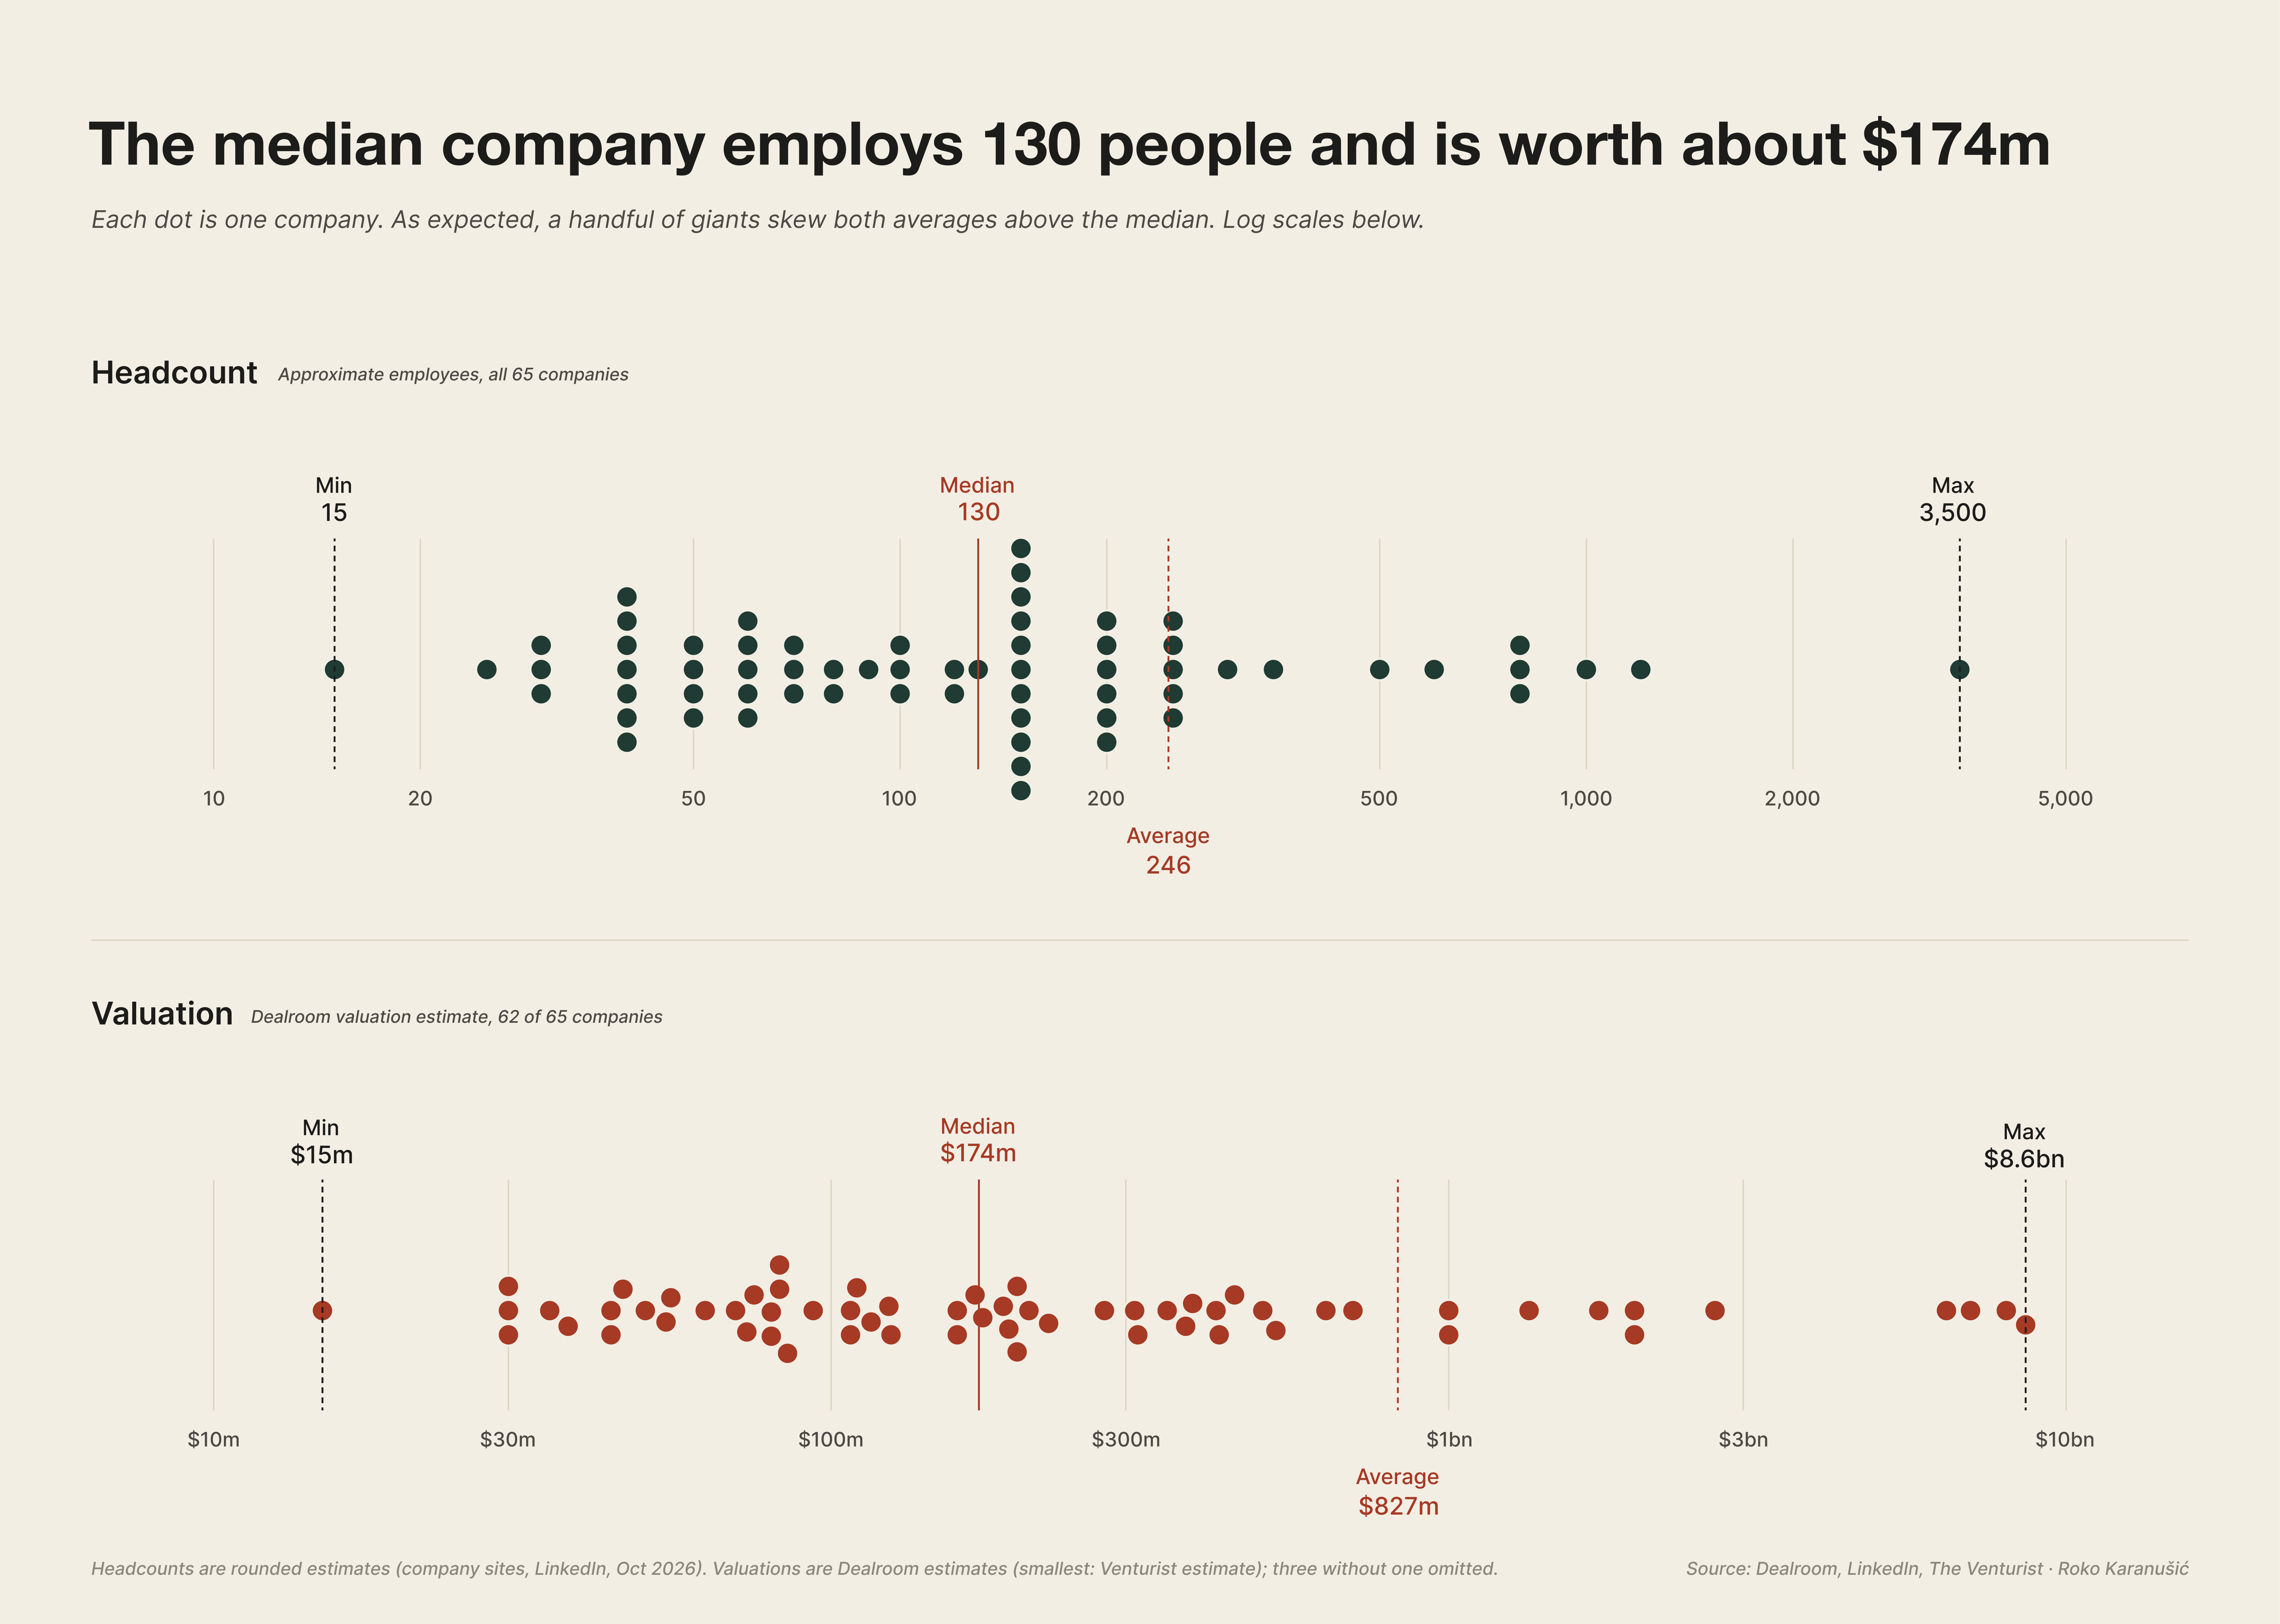
Most companies in our selection employ between 50 and 200 people, with a median headcount of 130, which is more than we expected. The median valuation figure of $174 million indicates that there is a high degree of growth expectations built into the valuations, although we believe that most of the final gains will be enjoyed by the best 10–20%, as affairs usually stand in venture capital.
Only eight companies employ more than 500 people. Three of our unicorns have reached billion-dollar valuations with fewer employees than that, which is remarkable given the convoluted practical work involved in robotics. These companies are being valued for technology that could eventually serve entire industries, while their teams still number in the hundreds.
Our list abounds with unicorns: ten companies carry announced or credibly reported billion-dollar valuations, with two more waiting in the wings. Genesis AI is reportedly in talks to raise a staggering $500m at a $3bn pre-money valuation. Distalmotion’s valuation is not publicly disclosed, but it’s reasonable to conclude they also belong in the club, considering they have raised nearly $400m to date, including a $150m Series G last year.
Seven of the ten startups4 raised new rounds and received new, higher valuations in 2026. Including Genesis AI’s pending round would bring that number to eight.
At the top is Wayve, a truly global autonomous-driving company whose AI Driver has been tested in more than 500 cities worldwide. Quantum Systems follows closely, with TEKEVER in fourth place. Both have substantial defence businesses, riding Europe’s renewed appetite for defence investment. Including Helsing and STARK would have given defence four of the top six places.
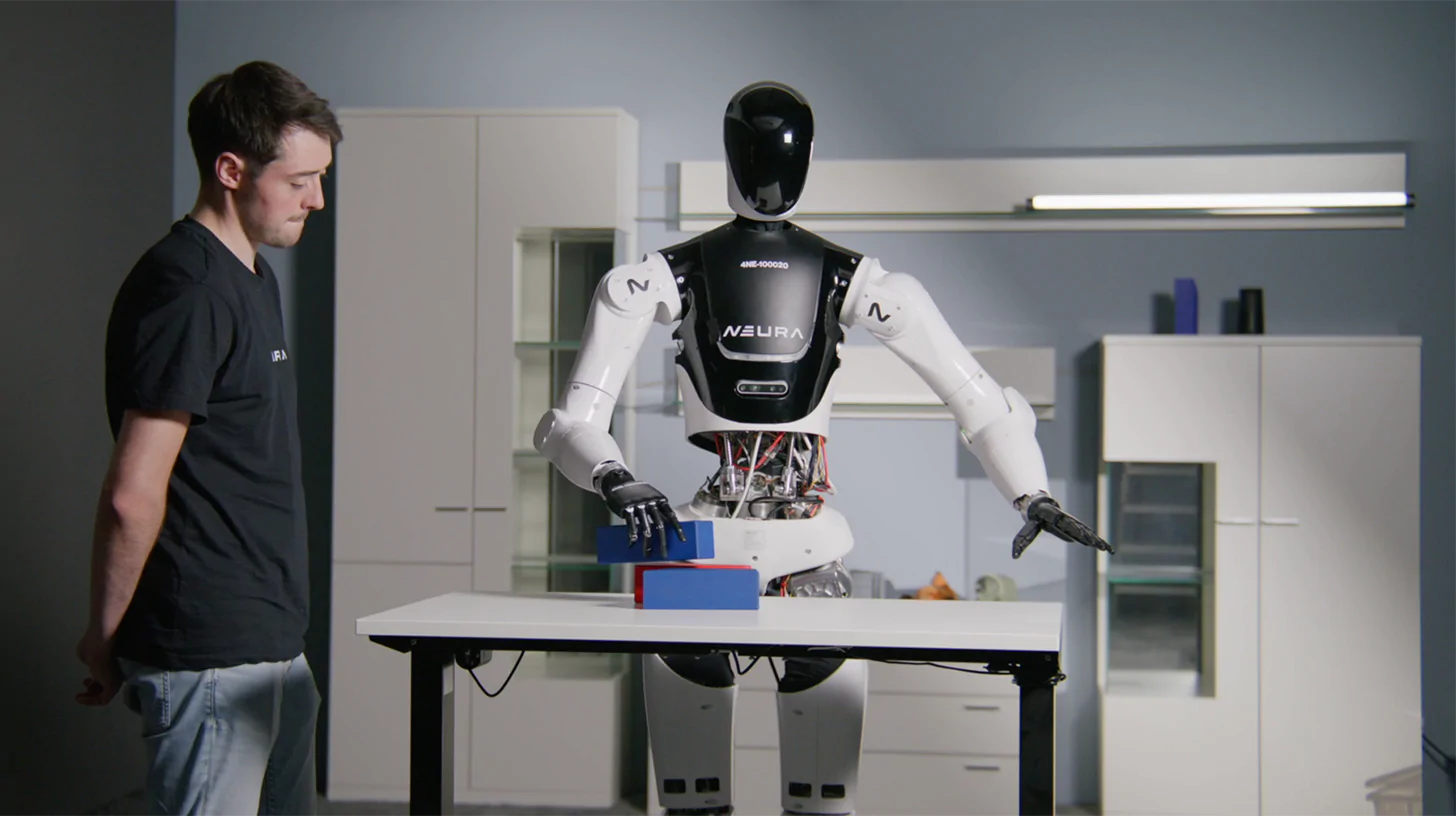
Third place belongs to NEURA Robotics, valued at a reported $7bn and our highest-valued European contender in the humanoid race dominated by China and the US.
The newest unicorn is Munich-based RobCo, which announced its unicorn-making secondary share sale while we were writing this article. Congratulations to the team!
Funding rounds
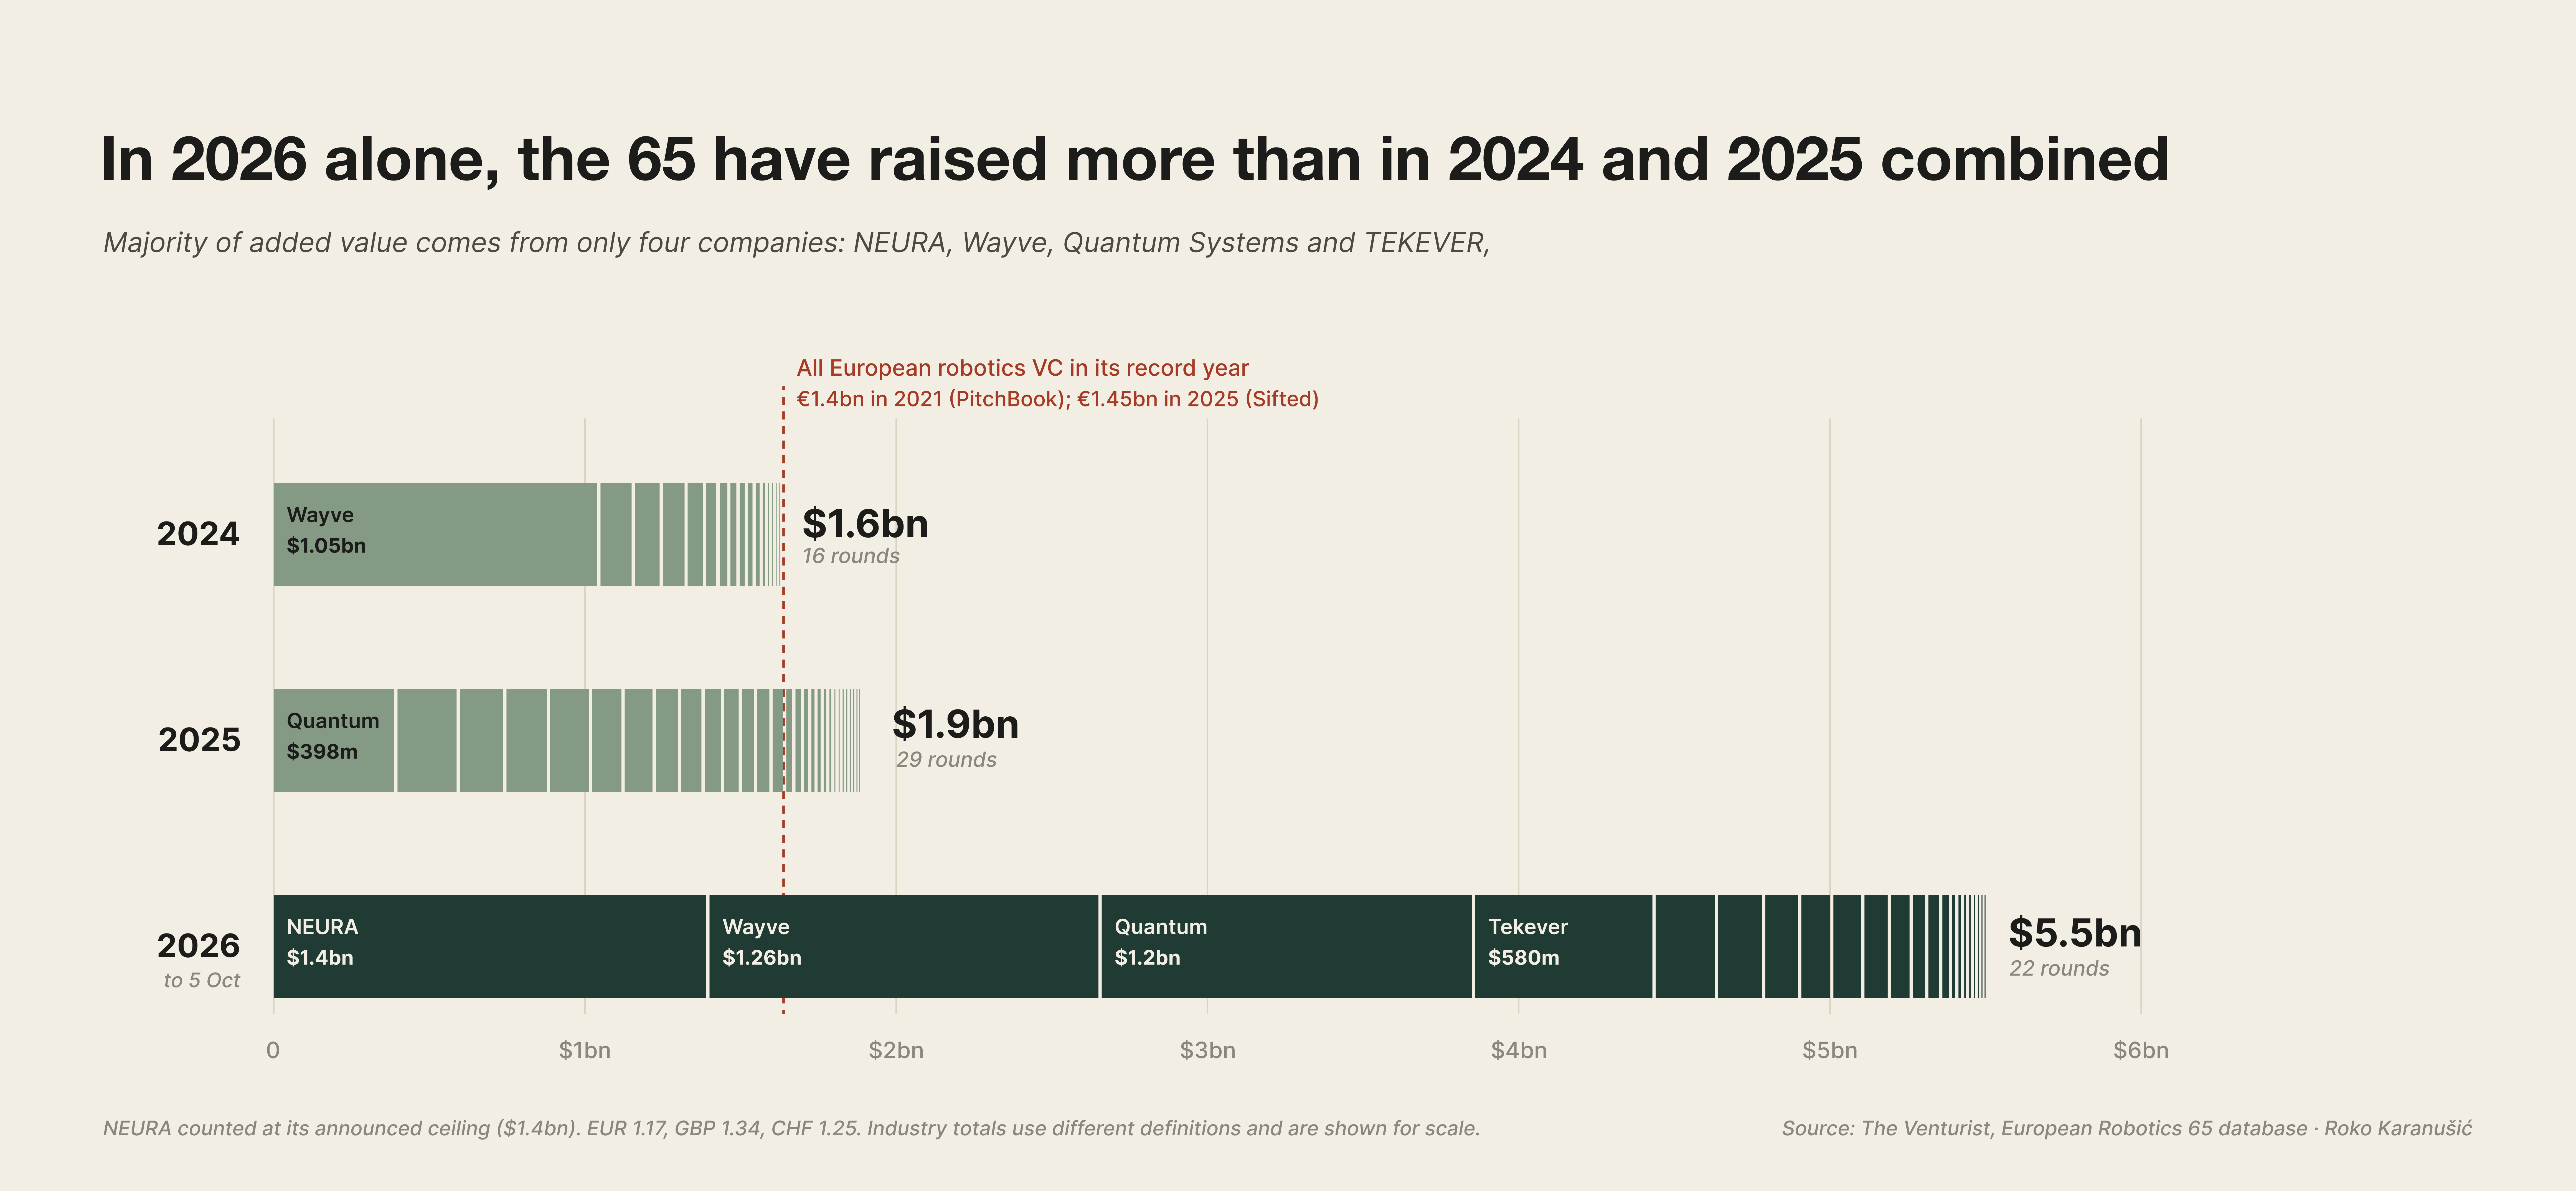
Investors’ appetite to go all-in has grown considerably. The 2026 rounds in our database add up to almost $5.5bn in fresh capital, counting NEURA’s announced ceiling. A large share of that money is concentrated in a few companies: NEURA, Wayve and Quantum Systems account for roughly 70% of the total. Quantum Systems’ latest financing is approximately three times the size of its previous one.
Since 2024, our selection has recorded four $1bn+ financings and six exceeding $500m (counting Genesis AI’s pending one). Huge cheques are also becoming more common much earlier in a company’s life. Gravis Robotics raised a $200m Series A, while Humanoid secured $152m at the same stage.
For comparison, Distalmotion’s Series G brought in $150m. Though we should not compare apples with oranges here, it is remarkable to see young companies receive early-stage rounds of this size. UMA flawlessly raised a rumored $40M round with zero revenue to date. This risk-taking attitude brings fantastic news for both the European venture capital ecosystem and the robotics scene.
Investors’ increasing willingness to fund ambitious robotics projects pretty early and ahead of commercial maturity will make European startups competitive globally.
Hubs
First on our list are Zurich and Paris with eight companies each, followed by Munich with five. Together, these three cities make up almost a third of the entire list. Outside of these three, the distribution is fairly sparse: 28 other cities each feature only one company.
This clustering may be due to universities. In many cases, robotics requires heavy research before commercialisation, and universities have been instrumental in that process. When the company arises, it inherits all the accumulated knowledge and a team that is already accustomed to working together. Also, staying in proximity to such institutions allows them to have access to graduates skilled in exactly those disciplines.
Knowledge spillovers may be at work here as well. Engineers transferring from one neighboring company to another bring with them experience that their new employers would otherwise need to get through research and experiments. It has been shown that proximity of knowledge workers allows firms to be better innovators.
Zurich is a particularly amusing case. ETH was directly related with all Zurich-based selected firms, with seven out of eight companies being confirmed spin-offs. Gravis, one of their darlings, grew out of many years of research by several ETH groups, which led to the development of its autonomous excavation robots.
In Munich, there are also similar cases. For instance, the technology of RobCo was developed at TUM, while Agile Robots at DLR, the German Aerospace Center.
Paris cluster is also associated with universities, though not through a single technical one, but across multiple institutions:
The founders of Wandercraft, now also a humanoid company, attended École Polytechnique.
Sophie Cahen of Ganymed Robotics graduated from CentraleSupélec.
The idea for Moon Surgical robot came from surgeon Brice Gayet at Sorbonne University robotics lab.
Inbolt came to be through École Polytechnique and HEC.
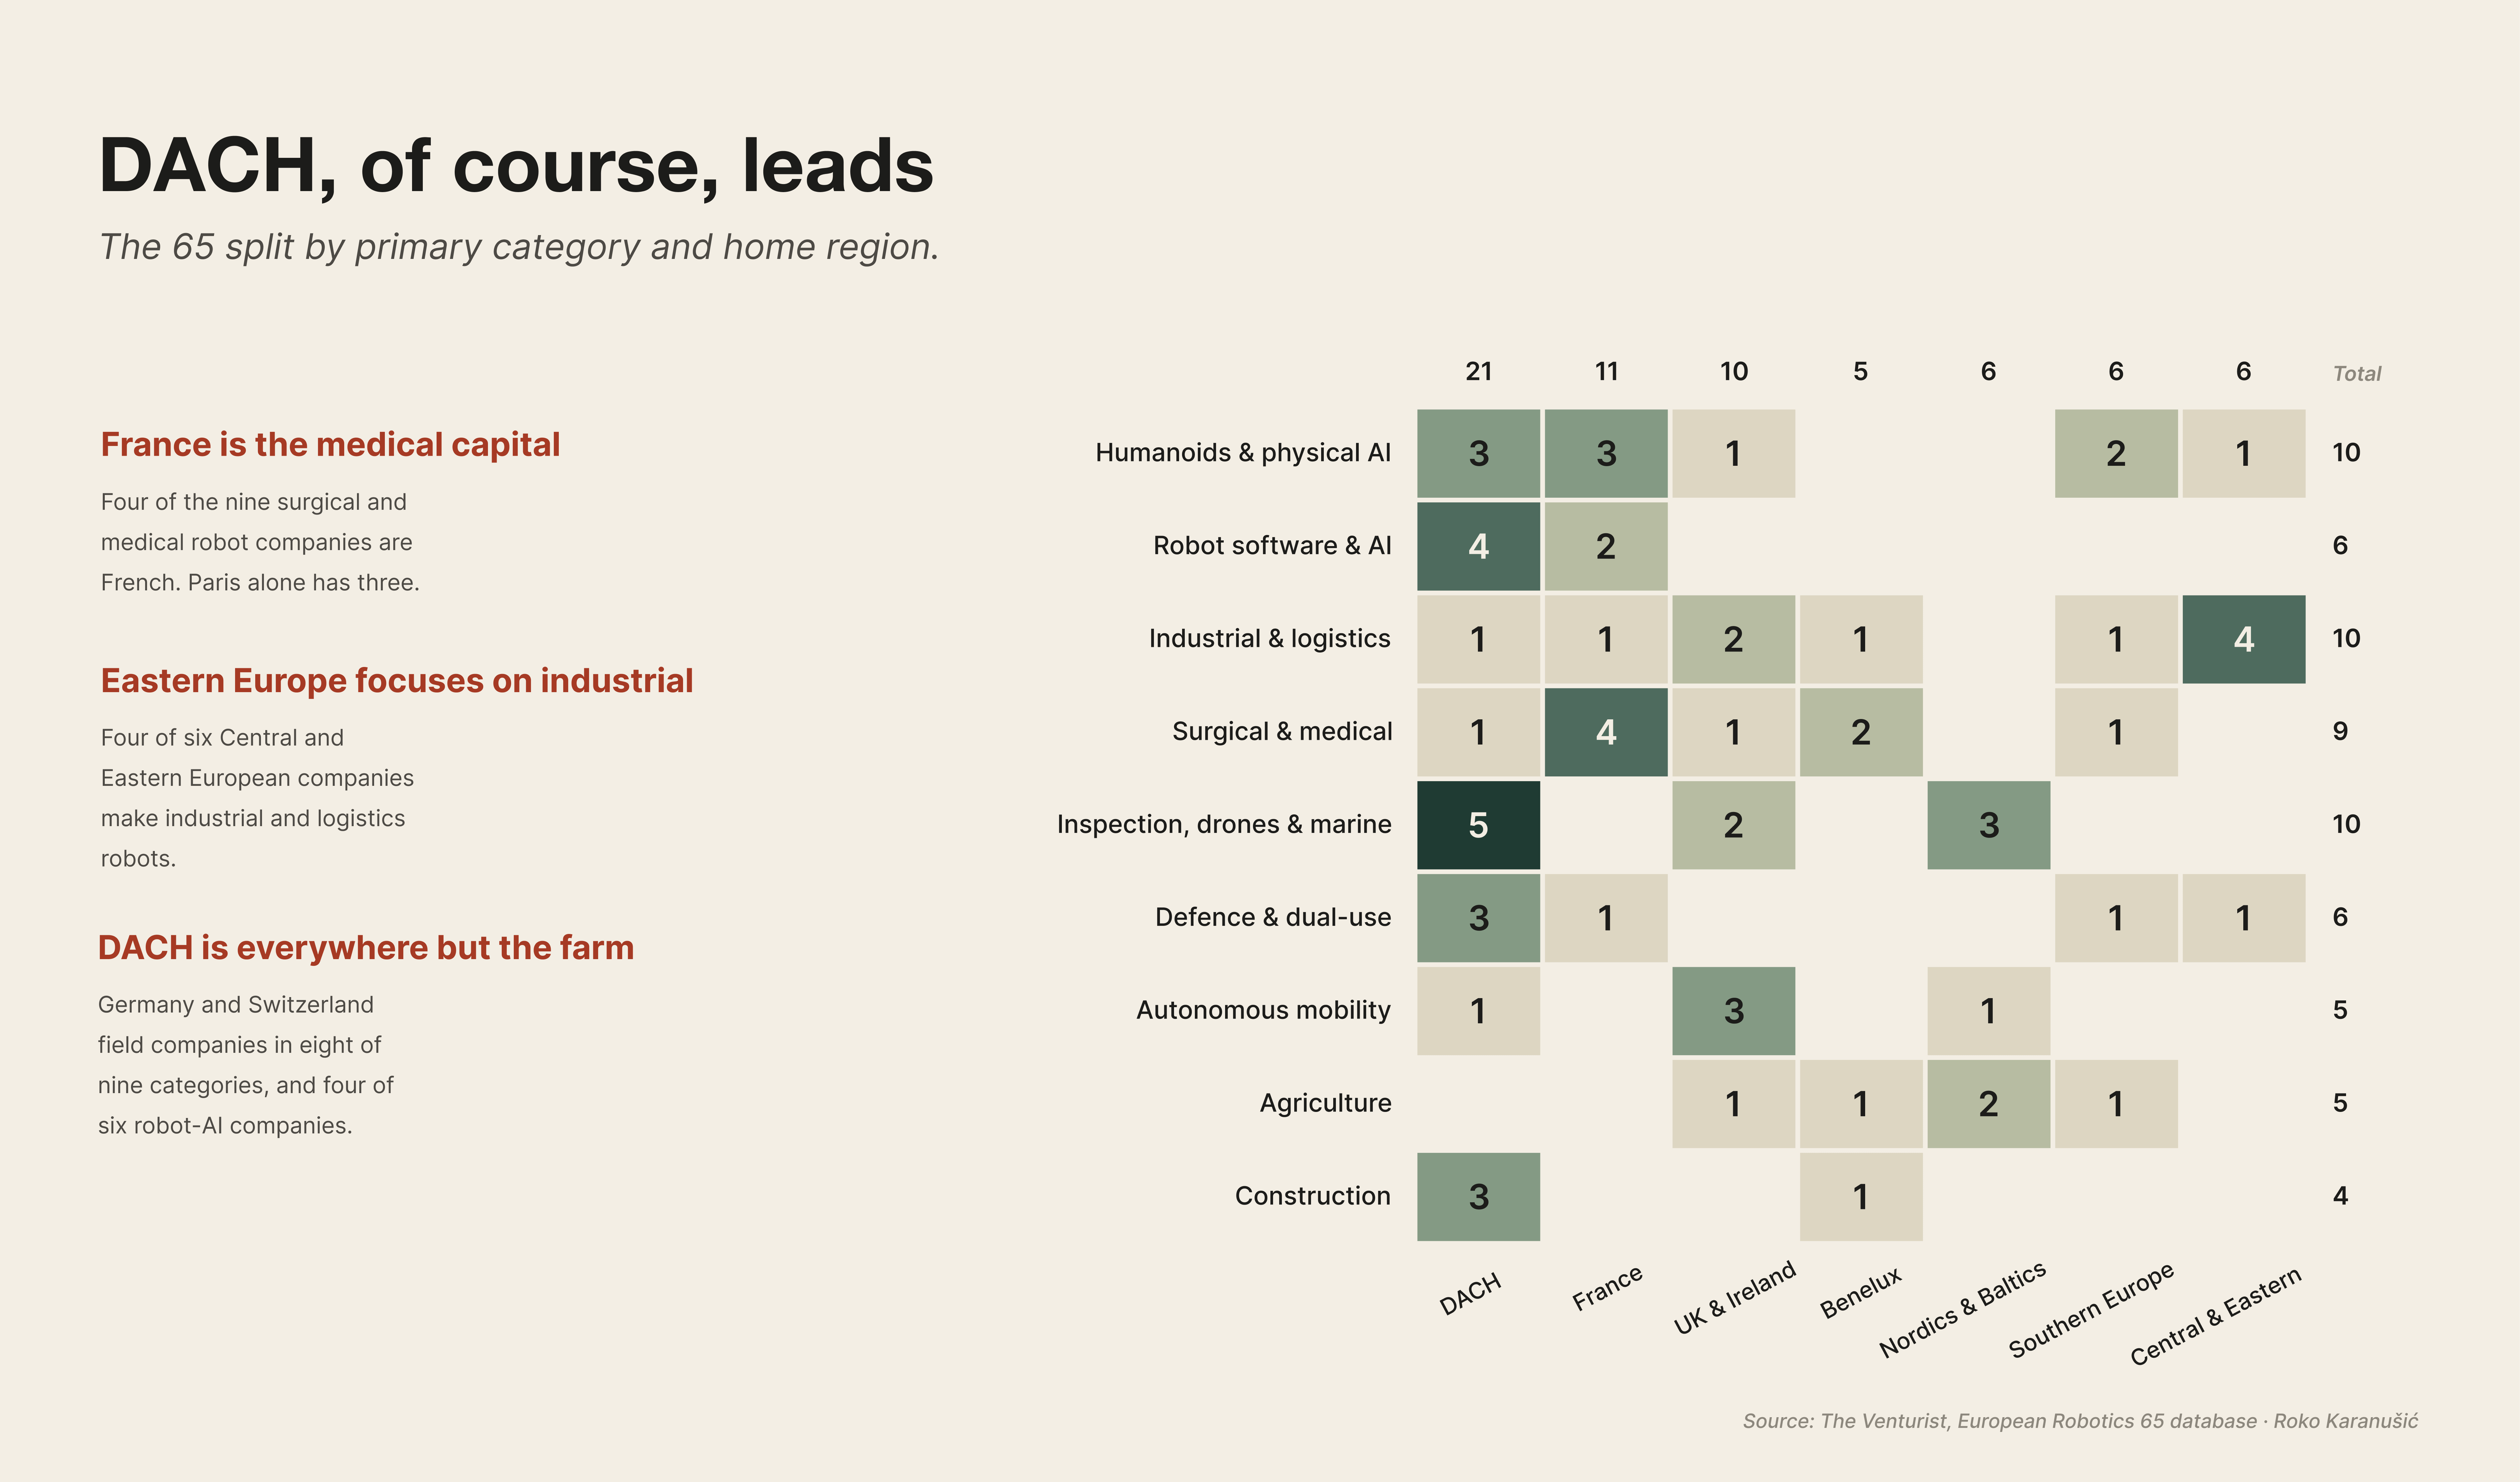
DACH region is expectedly the focal gravity point of Europe’s robotics. Germany and Switzerland provide us with 21 companies in the list and are the most versatile regions in the sense that they cover eight out of nine categories. Besides the physical robots, there are also four of our six robot-software and AI companies that deal with learning capabilities of robots and their movement. Remarkable.
France is the leading country in the medical field, having four out of nine companies in the domain of surgical and medical robotics, three of which have their headquarters based in Paris. Interestingly, even within this cluster itself, different companies work on different applications; so while Ganymed uses robotics in knee surgery, Moon Surgical specialises in laparoscopy, and Robeauté designs miniature robots that are able to navigate brain tissues. What a tech!
Humanoids
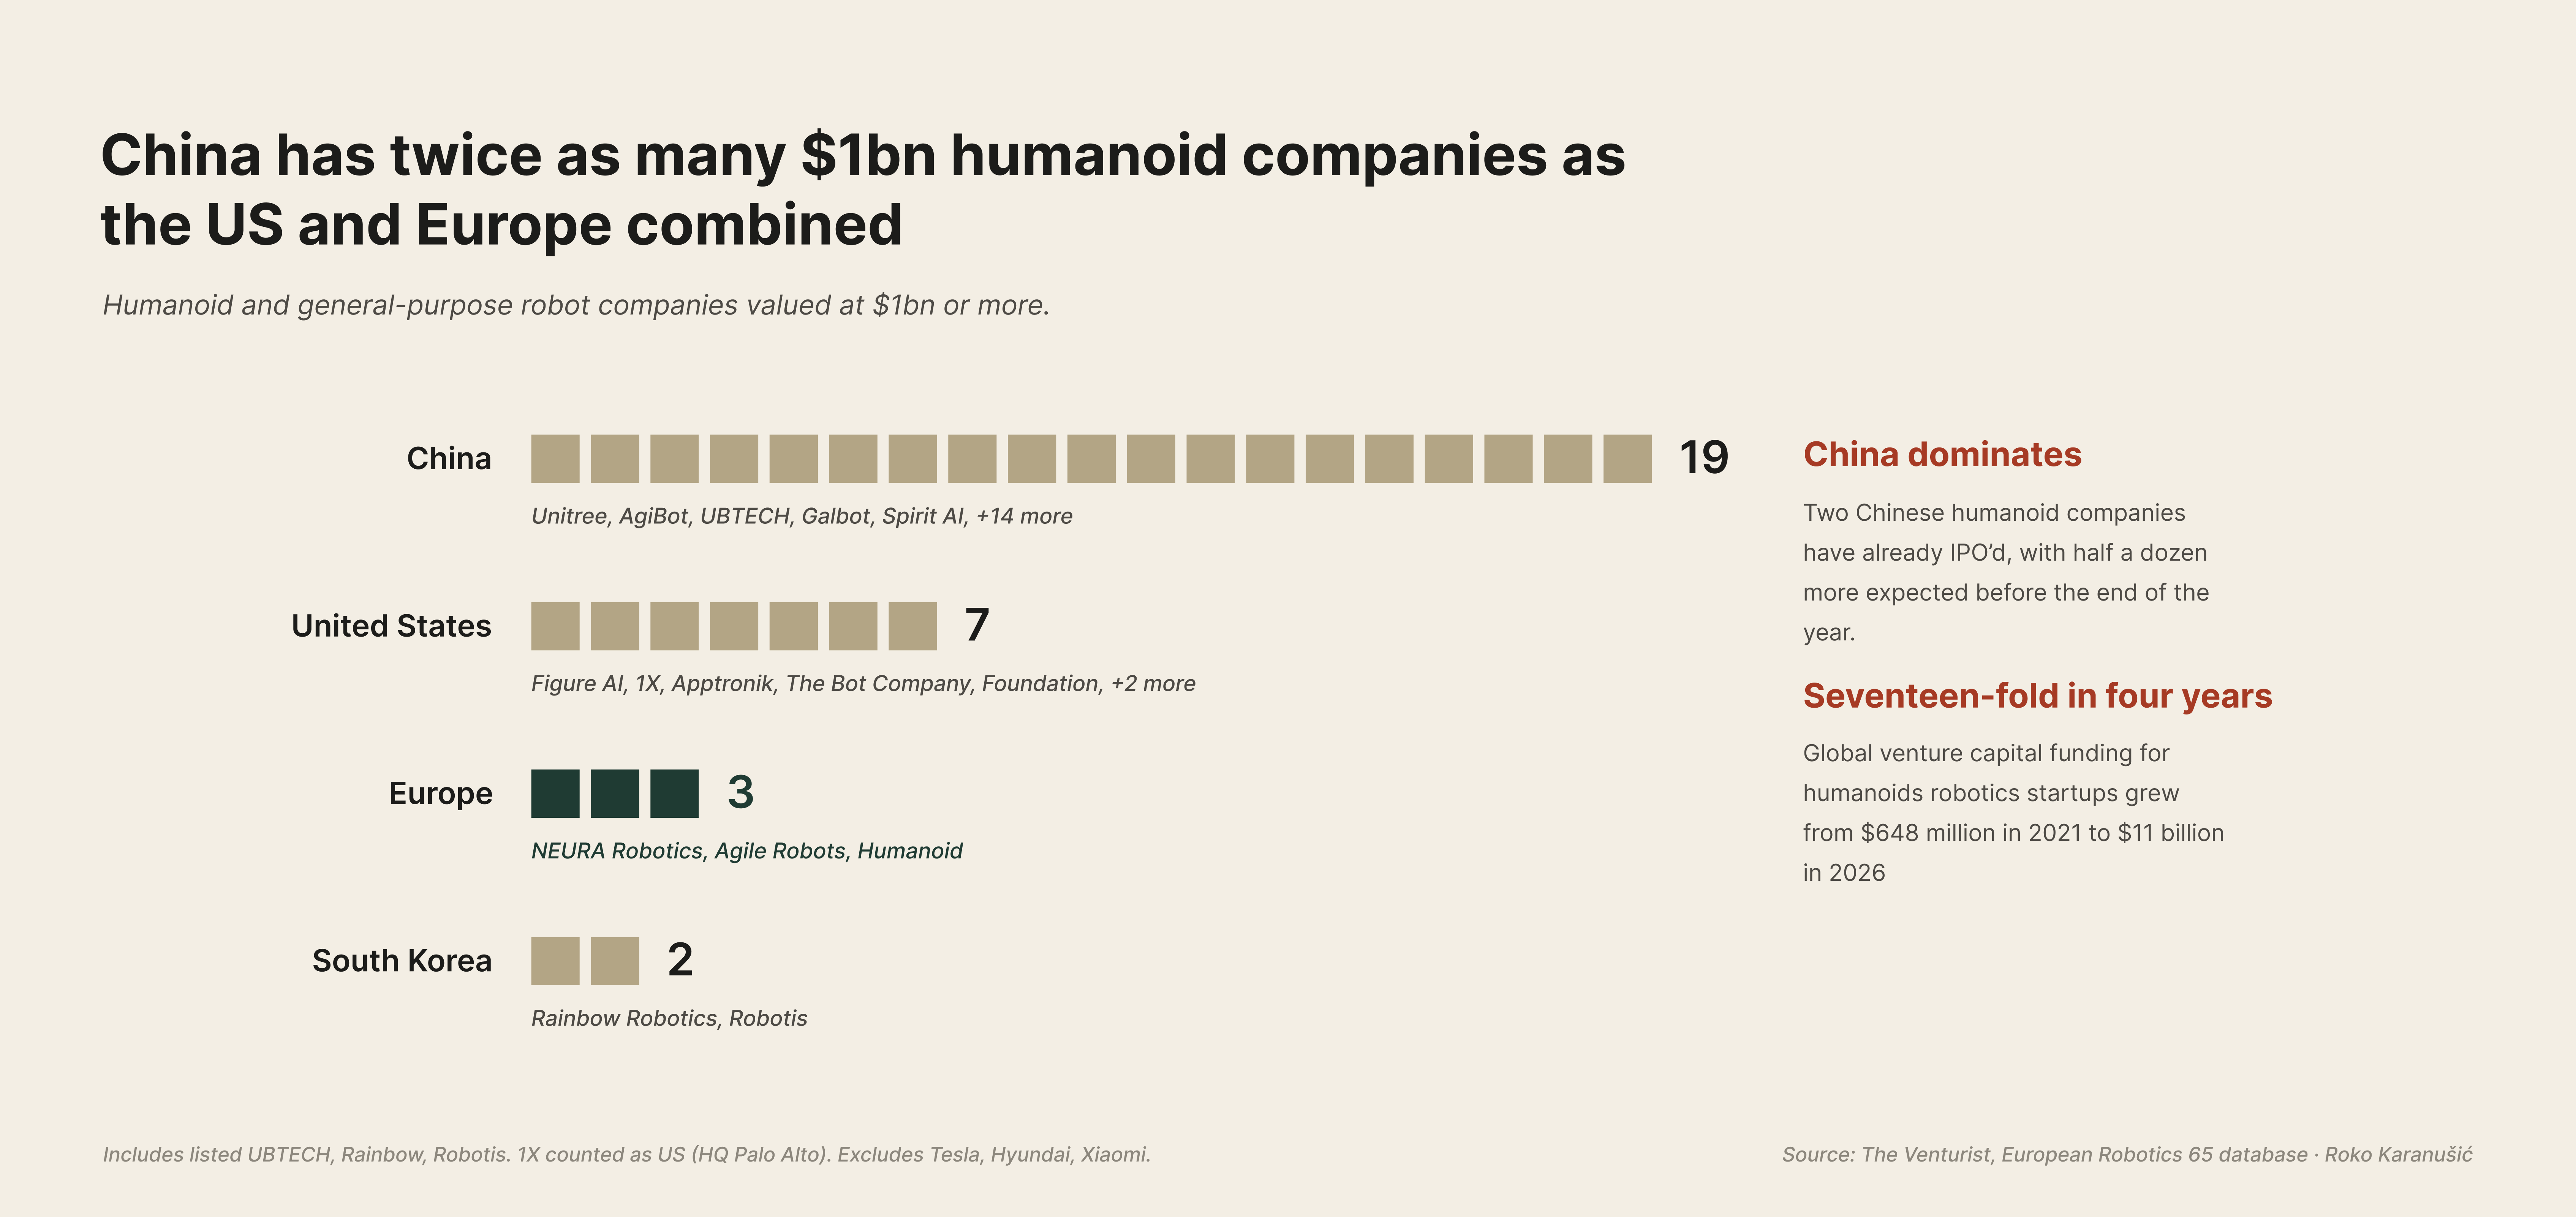
China’s lead in humanoid production against the rest of the world is jarring. Our comparison counts nineteen billion-dollar humanoid and general-purpose robotics companies in China, against seven in the US and three in Europe. Unitree, AgiBot and UBTECH are among the most prominent Chinese names, while Europe’s contingent consists of NEURA Robotics, Agile Robots and Humanoid.
Why is China so far ahead?
The majority of China’s advantage derives from their industrial muscle, which has been developed over years. Companies in robotics have already received the benefit of having suppliers at their disposal and engineers capable of making sophisticated hardware on mass scales.
This provides them with a considerable head start, compared to their Western counterparts, when it comes to translating ideas in good quality products – a challenge that has brought many hardware ventures to grief. It is this combination of manufacturing facilities and engineering skills, along with strong suppliers’ network that makes China untouchable at the minute.
Furthermore, government’s support provides even more impetus for the development, with public funds supporting the sector and local authorities helping to get all the players on board, China uses the same model as they did in their pretty formidable EV and solar industries.
Unitree, for example, has shipped 5,500 humanoid units in 2025 alone, with cumulative shipments over 10,000. It may not sound like a lot, but it constitues 40% of entire global humanoid market share. It was certainly enough for them to IPO in August this year.
[…]
The ambition we have found among our 65 gives us considerable confidence in what Europe can contribute. We’re looking forward to seeing these companies become part of the ordinary workings of the continent.
Disclaimer: This article is for informational and editorial purposes only. It does not constitute investment advice, legal advice, financial promotion, or a recommendation to buy, sell, fund, or work with any company mentioned. The analysis is based on publicly available information, company materials, interviews, and other sources believed to be reliable at the time of writing, but The Venturist does not guarantee the completeness or accuracy of all information. Any errors or omissions are unintentional and will be corrected where appropriate. Views expressed are those of the author unless stated otherwise.
Google DeepMind reported in June 2025 that Gemini Robotics On-Device could adapt to new manipulation tasks with as few as 50–100 demonstrations. For comparison, their 2023 RoboCat model could require hundreds to 1,000 human demonstrations, followed by thousands of autonomous practice runs.
Paris actually has a similar pattern, but across several institutions rather than one dominant university. Wandercraft and Inbolt emerged from École Polytechnique’s ecosystem, while Moon Surgical commercialised technology developed at Sorbonne’s ISIR robotics lab.
General-purpose robots will probably enter the market by doing one narrow job well, then expand into more tasks as the technology improves. The bet behind humanoids is that one adaptable machine can eventually replace several specialised robots, making it more useful and economical over time.
Eight out of twelve if we count Genesis AI’s pending round and Distalmotion’s estimated valuation range.